
Category: Accountancy
-
Recruiting, Developing and Retaining the Next Generation of Accountants: A Practical Playbook
Why the Accounting Talent Pipeline Is Under Pressure Fewer students are entering accounting programs. Young professionals want different career paths than past generations, and firms struggle to fill open roles. These trends connect and reshape how the accounting profession finds and keeps talent. Declining Entry Into the Accounting Profession Bachelor’s degrees in accounting have dropped…
-

Making Tax Season Less Stressful: A Capacity Planning Guide
Build a Tax Season Capacity Baseline Firms need real numbers from past tax seasons before planning for peak workloads. Reliable capacity planning begins with data on volume, hours worked, and where time gets lost. Audit Prior-Season Volume, Hours, and Delays Firms should pull last season’s numbers before making staffing decisions. They need to count how…
-
Smarter Audits with AI: Enhancing Accuracy, Compliance, and Fraud Detection
Core Pillars of AI-Powered Auditing AI-powered audits rely on a defined scope and measurable gains over manual methods. They also deliver clear improvements in audit accuracy and audit efficiency. These pillars guide how artificial intelligence in auditing supports risk assessment, compliance, and fraud detection. Defining AI Audits and Their Scope An AI audit uses machine…
-

Choosing the Right Cloud Accounting Technology Stack
Core Stack Architecture and Selection Criteria A strong accounting tech stack starts with clear goals, not software features. Firms that choose tools based on actual workflow needs avoid data silos and get better ROI from every platform they use. Define Firm Goals, Service Mix, and Workflow Bottlenecks Before choosing any software, a firm should map…
-
Mastering the Books: Core Bookkeeping Skills for Accountants
Understanding Bookkeeping and Accounting Fundamentals Bookkeeping and accounting work together to create accurate financial records. They serve different purposes in managing a company’s money. The accounting equation provides the mathematical foundation that keeps all financial data balanced and reliable. Differentiating Bookkeeping and Accounting Roles Bookkeepers record daily financial transactions. They enter invoices, track payments, and…
-

In What Ways Do Anti-Money Laundering Regulations Impact Financial Institutions’ Accounting Practices?
Overview of Anti-Money Laundering Regulations Anti-money laundering regulations are critical in detecting, preventing, and deterring illegally obtained funds from entering the legitimate financial system. They create an accountability framework for financial institutions to follow, ensuring the integrity of the financial markets. Historical Context Anti-money laundering (AML) initiatives evolved as responses to organized crime and financial…
-

What are the Reporting Requirements for Operating Leases under ASC 842/IFRS 16: A Comprehensive Overview
Understanding the New Lease Accounting Standards The new lease accounting standards, ASC 842 and IFRS 16, have redefined how entities report lease transactions, creating a significant impact on the balance sheets of lessees and lessors. Overview of ASC 842 and IFRS 16 ASC 842, known as the Accounting Standards Codification Topic 842, and IFRS 16…
-
Practice Performance Metrics Every Accounting Firm Leader Should Track
Build a Focused KPI Framework Accounting KPIs only help decision-making when they are few, tied to realistic targets, and reviewed regularly. Leaders need to separate metrics that predict problems from those that only confirm them. Avoid metrics that look good but mean little, and keep data up to date with a set schedule. Separate Leading…
-
Debits vs Credits Explained: The Foundation of Double-Entry Accounting
Understanding the Core Concepts of Debits and Credits Debits and credits form the foundation of accounting. Accountants use them to record every transaction with equal entries on both sides. This system maintains balance by increasing some accounts while decreasing others. It creates a complete financial picture of business activities. Definition of Debits and Credits A…
-

How Does the Fair Value Measurement (Topic 820) Shape Asset and Liability Valuation under U.S. GAAP?
Understanding Fair Value Measurement Fair Value Measurement, defined in Topic 820 of the U.S. Generally Accepted Accounting Principles (GAAP), establishes the framework for measuring assets and liabilities at fair value. The Financial Accounting Standards Board (FASB) outlines the principles and requirements for how entities should measure and disclose these values. Fair value under GAAP refers…
-
Why Every Debit Needs a Credit: Unlocking Financial Balance in Accounting
Fundamentals of Debits, Credits, and the Double-Entry System Every financial transaction includes two entries that balance each other. The system uses the accounting equation and clear rules for debits and credits. Origins and Principles of the Double-Entry Accounting System Double-entry accounting ensures that every transaction affects at least two accounts. When companies record financial events,…
-
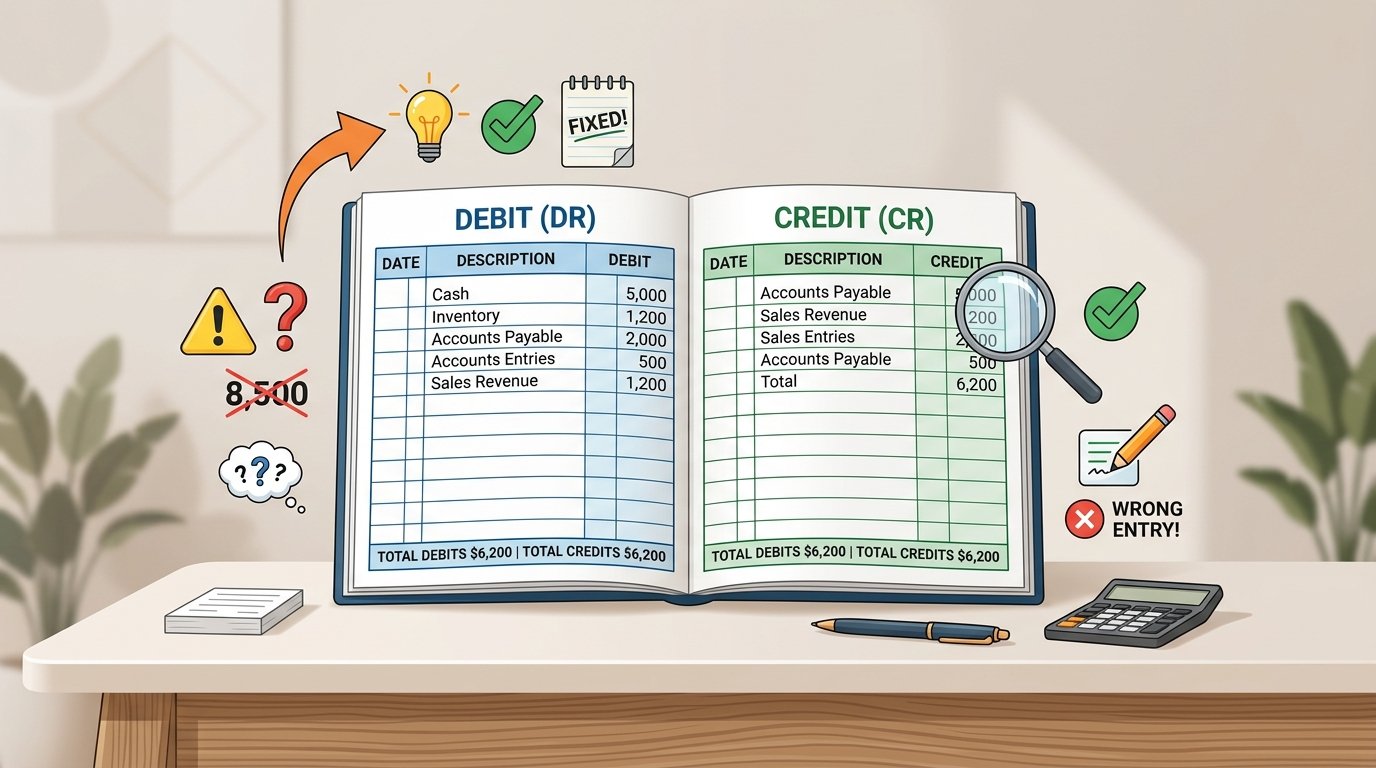
Common Debit and Credit Mistakes: Avoid Costly Financial Errors
Understanding Debit and Credit Fundamentals Debits and credits are the backbone of accounting. Debits always go on the left side of an account, and credits go on the right side. Every transaction affects at least two accounts. The total debits must equal total credits to keep the books balanced. Key Differences Between Debit and Credit…
-

What are the Accounting Implications of FATCA for Foreign Financial Institutions: A Comprehensive Analysis
Overview of FATCA The Foreign Account Tax Compliance Act (FATCA), enacted in 2010, is critical U.S. legislation aimed at preventing tax evasion by U.S. citizens, residents, and entities through the use of offshore accounts. Under FATCA, foreign financial institutions (FFIs) are required to report information on accounts held by U.S. taxpayers to the Internal Revenue…
-

How the Dodd-Frank Act Provisions Impact Derivatives Accounting and Reporting
Overview of the Dodd-Frank Act The Dodd-Frank Wall Street Reform and Consumer Protection Act was established in response to the 2008 financial crisis. Designed to prevent a repeat of the crisis, this sweeping legislation introduced numerous regulatory changes aimed at increasing oversight and enhancing risk management practices within the financial industry. The Act’s creation signified…
-

What Are the Implications of Basel III Regulations on Banks’ Capital Adequacy and Liquidity: An In-Depth Analysis
Overview of Basel III Framework Basel III is an international regulatory framework developed by the Basel Committee on Banking Supervision in response to the shortcomings exposed by the global financial crisis of 2007-09. It seeks to fortify banks against economic stress and to prevent future crises by enhancing their regulation, supervision, and risk management. Capital…
-

How Does the Sarbanes-Oxley Act Shape Internal Controls and Financial Transparency?
Introduction to Sarbanes-Oxley Act In the wake of early-2000s financial scandals, Congress enacted the Sarbanes-Oxley Act (SOX) in 2002. This act targets corruption in corporations by setting new standards for all public companies and accounting firms in the United States. It was named after its sponsors, Senator Paul Sarbanes and Representative Michael Oxley, and has…
-

What are the Accounting Considerations for Revenue Recognition: Navigating ASC 606 Standards
Overview of ASC 606 The Accounting Standards Codification (ASC) Topic 606, “Revenue from Contracts with Customers,” is a revenue recognition standard that provides a framework for businesses to recognize revenue in a consistent and comparable manner. This standard was jointly developed by the Financial Accounting Standards Board (FASB) to replace previous industry-specific guidance. Under ASC…
-

How Does the SEC’s Regulation S-X Shape Public Company Financial Reporting Requirements?
Overview of Regulation S-X Regulation S-X sets forth the principles and requirements for financial statements that are submitted by public companies to the Securities and Exchange Commission (SEC). It defines the form and content of these essential disclosures. Purpose and Scope The main purpose of Regulation S-X is to prescribe the form and content of…
-

What Are the Tax Accounting Implications of the Tax Cuts and Jobs Act for Corporate Entities: A Detailed Analysis
Overview of the Tax Cuts and Jobs Act The Tax Cuts and Jobs Act (TCJA), enacted in December 2017, has been one of the most substantial reforms to the United States tax code in decades. It includes various modifications that broadly impact the economy, businesses, and the job market. One of the primary changes introduced…
-

How Debits and Credits Impact Financial Statements: Principles and Applications
Essential Concepts of Debits and Credits Debits and credits form the foundation of double-entry accounting. Every transaction affects at least two accounts. The accounting equation (Assets = Liabilities + Equity) stays balanced because each debit entry matches a credit entry of equal value. Understanding the Accounting Equation The accounting equation shows the relationship between what…